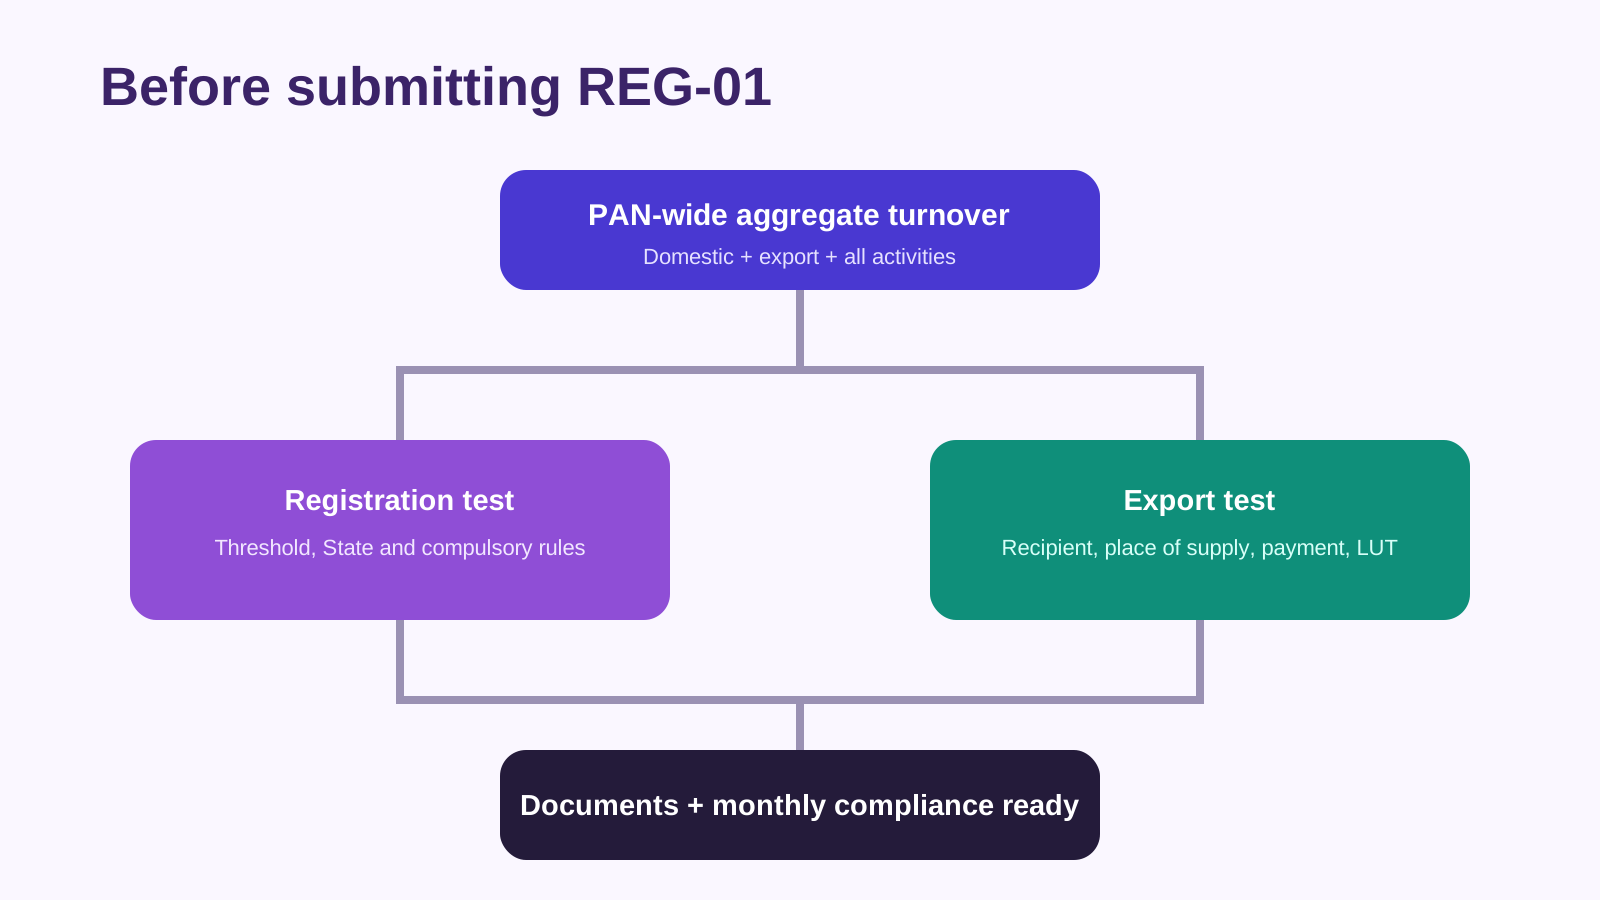
A freelancer should not register only because one client asks for a GSTIN, and should not stay unregistered only because payments come from abroad. The decision starts with PAN-wide aggregate turnover, the State, the exact services supplied and any compulsory-registration rule.
The direct answer
The ordinary GST registration threshold for suppliers of services is generally ₹20 lakh, with a lower threshold in specified special-category States. Aggregate turnover is PAN-wide and includes taxable, exempt, export and inter-State supplies as defined, even where a qualifying export is zero-rated.
Notification 10/2017-Integrated Tax exempts many persons making inter-State taxable services from registration until the applicable threshold is crossed. That means “one inter-State client always requires GST registration” is not a safe rule. Other compulsory-registration provisions and the actual activity can still change the result.
Map every income stream first
List domestic clients, overseas clients, marketplace/platform receipts, commission, retainers, reimbursed costs and any goods sold alongside services. Record customer location, service description, contract value and the State from which the work is supplied.
Do not test separate trade names or platforms independently when they belong to the same PAN. A designer with ₹13 lakh of domestic work and ₹9 lakh of qualifying export services does not test only the ₹13 lakh domestic figure.
Overseas clients are a second legal test
A customer outside India does not automatically create an export of services. Section 2(6) of the IGST Act requires the supplier to be in India, recipient outside India, place of supply outside India, permitted receipt of payment and parties that are not merely establishments of the same person.
Intermediary and other special place-of-supply rules can affect the result. Verify the contract and actual role before calling the supply zero-rated.
If the service qualifies as export and the freelancer is registered, the common no-IGST route uses a valid LUT for the relevant financial year. Preserve the LUT acknowledgement, export invoice, contract and remittance/payment evidence.
Worked example
An independent technical consultant in Maharashtra earns ₹16 lakh from Indian businesses and ₹7 lakh from a German customer. PAN-wide aggregate turnover is ₹23 lakh; the foreign receipt is not omitted merely because a qualifying export may be zero-rated.
Before registration, the consultant verifies the nature of both supplies and when liability arose. After registration, Indian invoices follow the applicable place-of-supply and tax rules. The German engagement is treated as export only after every Section 2(6) condition is documented; if supplied under LUT, the annual LUT acknowledgement stays with the invoice file.
Documents to prepare
- PAN, photograph and valid contact details;
- constitution or proprietorship evidence as applicable;
- principal-place ownership or occupancy proof;
- bank details and authorised-signatory evidence;
- PAN-wide turnover working by revenue stream;
- customer location and place-of-supply analysis;
- overseas contract and payment/remittance evidence;
- service descriptions and any marketplace agreements; and
- existing registrations or business activities in other States.
After registration
Registration creates continuing duties. Use the GSTIN on applicable invoices, issue the correct document, review place of supply, file applicable returns even where a period is nil, reconcile sales and purchases, and preserve acknowledgements. Voluntary registration also brings the registered-person obligations from its effective date.
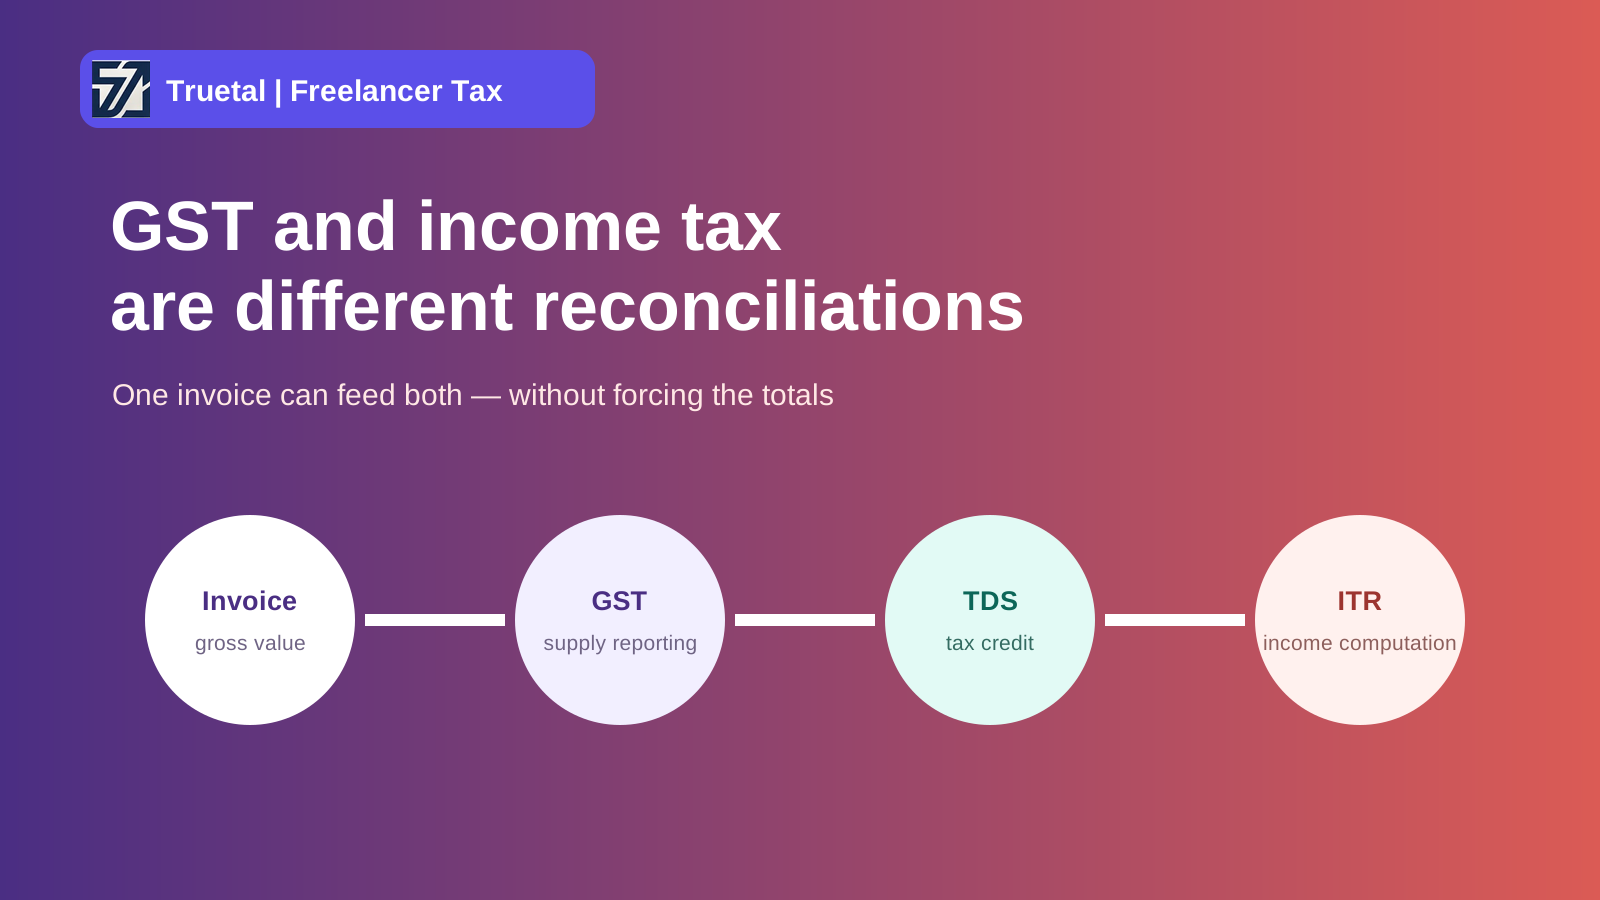
Keep accounting and GST decisions separate. A genuine business expense may belong in the books while GST ITC remains subject to invoice, business-use, GSTR-2B and statutory eligibility conditions.
Common mistakes
- Checking only Indian revenue and ignoring exports in aggregate turnover.
- Treating every foreign customer as a zero-rated export.
- Using the outdated claim that every inter-State service needs registration from the first rupee.
- Applying without matching address and occupancy documents.
- Collecting GST before registration becomes effective.
- Filing the registration but not setting up invoice, return and reconciliation routines.
How Truetal helps
Accounting services for freelancers can organise the turnover working, invoices, payments and monthly records that continue after registration. Truetal does not decide legal eligibility or submit an application as an authorised GST practitioner without a separately agreed professional scope.
FAQ
Does every freelancer need GST registration?
No. Registration depends on PAN-wide aggregate turnover, the applicable State threshold, supply type, exemptions and compulsory-registration rules. Test all revenue streams together.
Do overseas clients count toward GST turnover?
Yes. Export turnover forms part of aggregate turnover even where a qualifying export is zero-rated.
Is GST registration compulsory for every inter-State service?
No. Notification 10/2017-Integrated Tax gives threshold relief to many inter-State suppliers of taxable services, but other compulsory-registration rules and the actual supply still need review.
Can I export services without charging IGST?
A registered person may commonly use a valid LUT to make a qualifying zero-rated export without payment of IGST. Every export condition and the current LUT process must be satisfied.
What should I prepare before applying?
Prepare PAN and identity records, principal-place evidence, bank and signatory details, a PAN-wide turnover working, client/supply classification and export evidence where relevant.
The takeaway
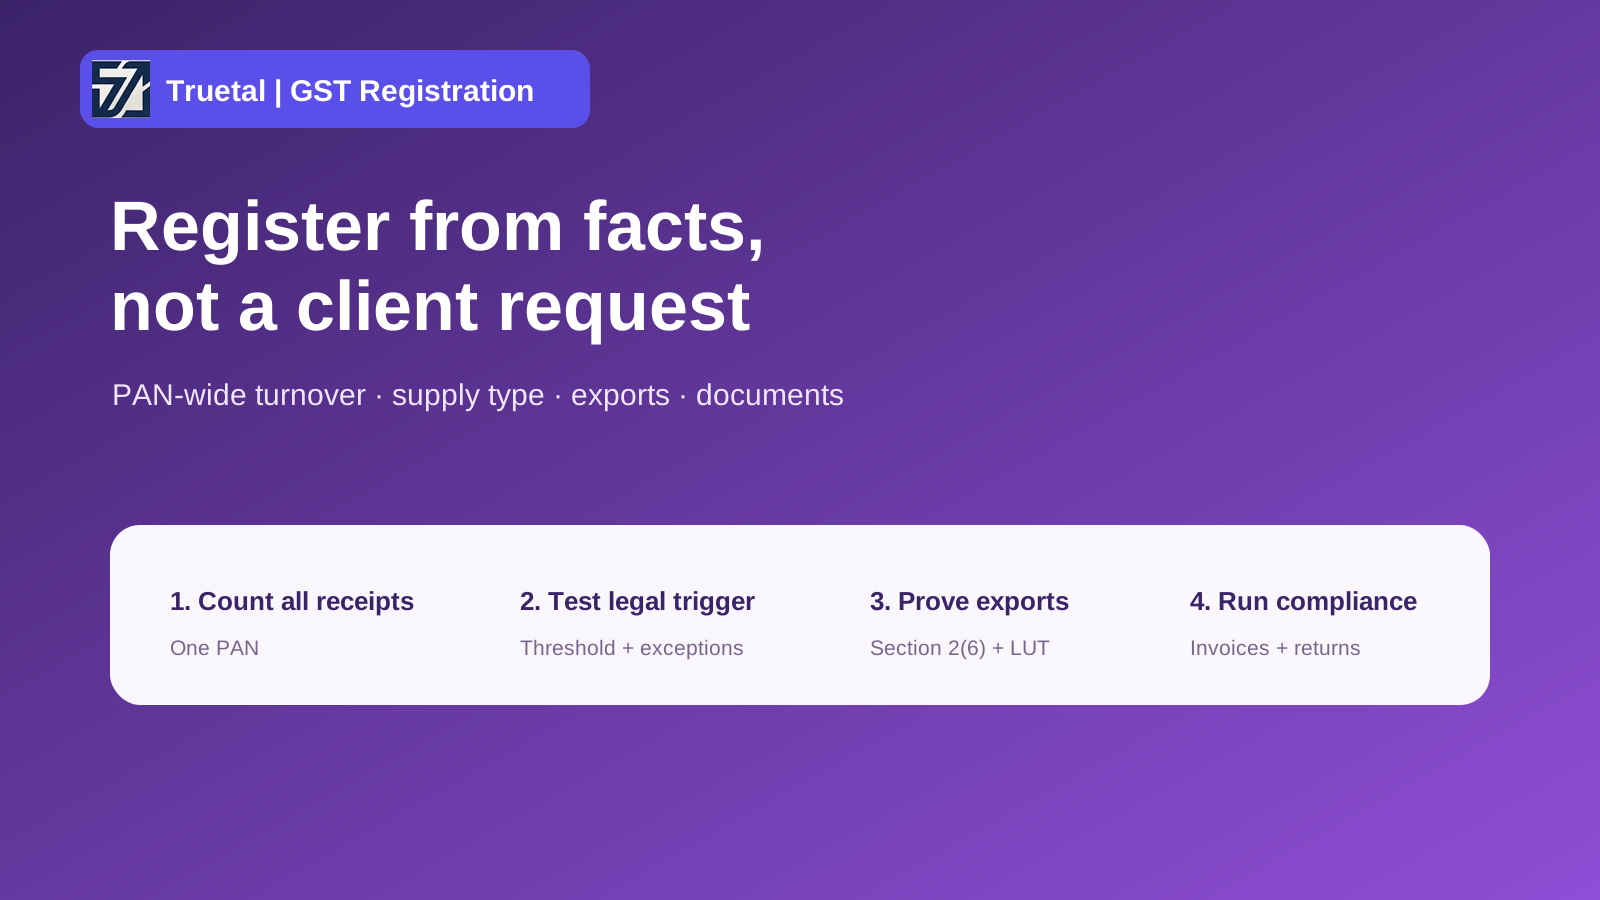
Register from a written facts file, not a client request or a social-media threshold. Count PAN-wide turnover, test the actual supply, prove export conditions and prepare the monthly compliance workflow before the GSTIN is issued.