The direct answer
Rule 14A is an optional registration route for eligible applicants whose monthly output tax on supplies to registered persons does not exceed ₹2,50,000. Before choosing it, prepare a month-wise B2B tax working, not an annual-turnover average. Before exiting it, distinguish REG-32 submission, the REG-33 order, and the first day of the following month when reporting above the limit becomes permitted under Rule 14A(11).
Current-law check: 19 October 2026. Notification 18/2025-Central Tax introduced Rule 14A from 1 November 2025. For withdrawal applications on or after 1 April 2026, the minimum-return condition is one tax period plus all returns due. This guide uses the active rule and GSTN's withdrawal advisory; examples are illustrative, not individual eligibility or filing advice.
Should you select Yes under Rule 14A?
First decide whether GST registration is required or appropriate under the ordinary provisions. Rule 14A does not replace that assessment or create a general ₹2.5 lakh turnover exemption.
An applicant under Rule 8 can consider the option after checking:
- The expected output tax on supplies to registered persons, month by month, across the relevant tax heads.
- Aadhaar authentication requirements and applicable exceptions under section 25(6D).
- Whether another Rule 14A registration already exists in the same State or Union territory against the same PAN; the rule restricts a second such registration.
- Whether known contracts or seasonal billing will push a coming month above the cap.
Upon successful Aadhaar authentication, Rule 14A(4) provides electronic registration within three working days from the date of submission of the application. That is not a private approval guarantee or a reason to choose an unsuitable option. A freelancer with a large milestone invoice should test that month, not only the monthly retainer or annual average. A tax adviser should resolve uncertain supply classifications before the declaration is made.
Build the monthly B2B output-tax working
Use an invoice-level schedule with GSTIN, original document number/date, supply period, recipient registration status, taxable value, tax heads, adjustment references and reviewer. Keep B2C and other supply classes visible in separate columns. Excluding a class from this particular B2B working does not make it exempt from other GST obligations.
Here is an illustrative October working for a domestic service business. An 18% rate is assumed only for the example; verify actual classification and rate.
| October records | Taxable value | CGST | SGST | IGST | B2B output tax counted |
| Intra-state supplies to registered clients | ₹7,00,000 | ₹63,000 | ₹63,000 | ₹0 | ₹1,26,000 |
| Interstate supplies to registered clients | ₹5,00,000 | ₹0 | ₹0 | ₹90,000 | ₹90,000 |
| B2B total | ₹12,00,000 | ₹63,000 | ₹63,000 | ₹90,000 | ₹2,16,000 |
Compensation cess is zero in this example; include it if applicable. The illustrative headroom is ₹34,000 (₹2,50,000 minus ₹2,16,000). ITC does not turn this into a test of net tax paid in cash. The bank balance and collection dates are not a substitute for the output-tax schedule.
Now compare the actual and forecast months:
| Month | Illustrative B2B taxable value at 18% | B2B output tax | Review conclusion |
| September 2026 | ₹10,00,000 | ₹1,80,000 | ₹70,000 below the cap |
| October 2026 | ₹12,00,000 | ₹2,16,000 | ₹34,000 below the cap |
| November 2026 forecast | ₹14,00,000 | ₹2,52,000 | ₹2,000 above the cap: escalate before assuming the option remains suitable |
Do not average these months into an eligibility answer. This forecast is a planning warning, not permission to defer invoices, alter recipient status or suppress tax. Give the reviewer the underlying contract, supply dates, invoices and working before the peak occurs.
Withdrawal has three different dates
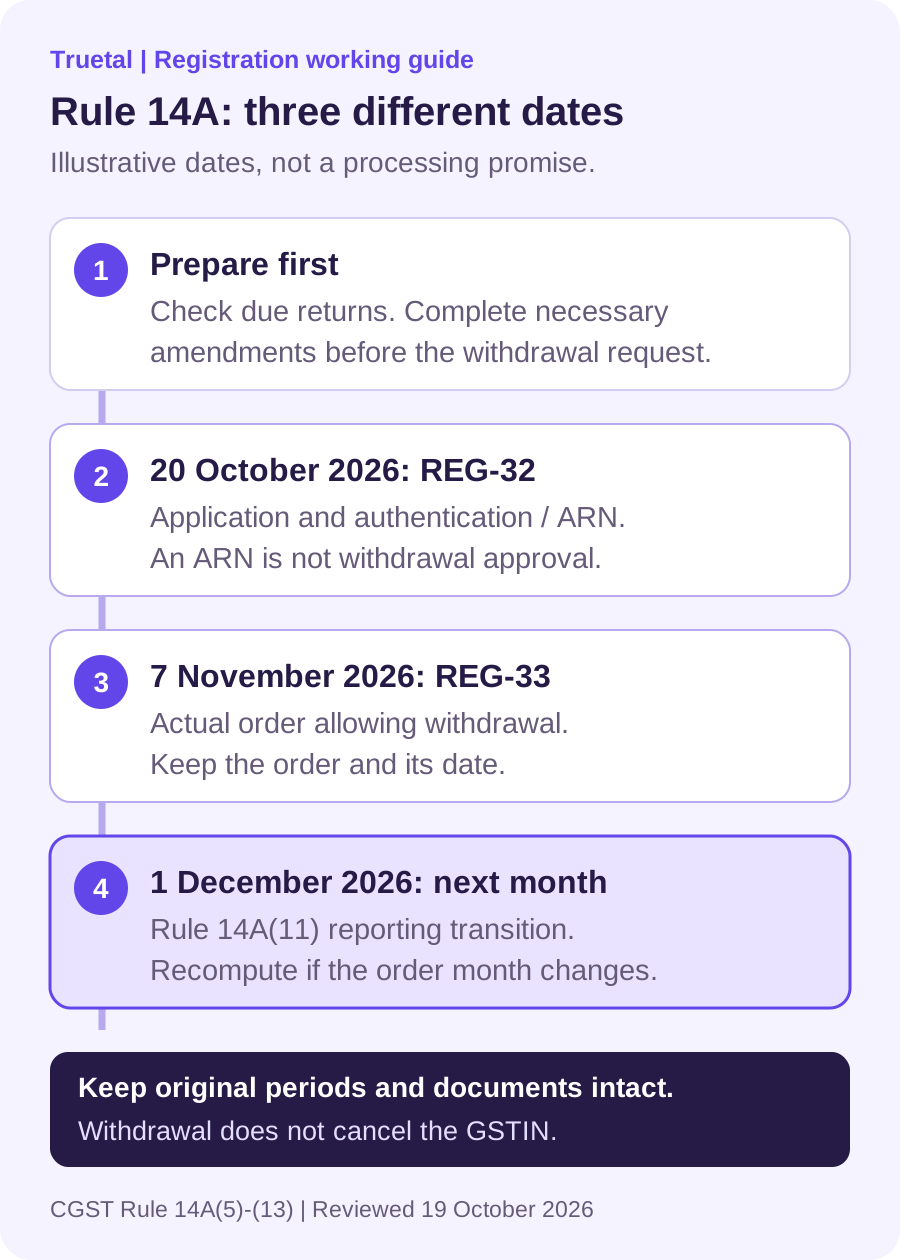
Assume an existing Rule 14A registrant has satisfied the return and other conditions. It files REG-32 on 20 October 2026 and receives the actual REG-33 order on 7 November 2026. Under Rule 14A(11), the first day of the succeeding month is 1 December 2026, not the application date and not 1 November.
| Checkpoint | Example | What it proves |
| REG-32 submission and authentication/ARN | 20 October 2026 | A withdrawal application exists; it is not an approval |
| REG-33 order allowing withdrawal | 7 November 2026 | The officer has allowed withdrawal; retain the order |
| Rule 14A(11) reporting transition | 1 December 2026 | Start of the month after the order month |
If the order arrives in a different month, recompute the transition from that actual order month. Do not assume a fixed processing date. Withdrawal from the option is not cancellation of the GSTIN.
In particular, an order on 7 November would not make the forecast November output tax of ₹2,52,000 reportable above the special cap under this transition. The permitted succeeding month in this illustration remains December. Escalate that mismatch before the forecast peak; do not assume the application or an expected order cures it.
Rule 14A(12) also restricts amendments that would take an earlier period above the specified limit. A later order is not a blanket cure for a prior-period breach. If the limit has already been exceeded or a return is blocked, preserve the complete records and obtain case-specific advice. Do not move an old invoice into a later month merely to make a portal summary pass.
Clear the withdrawal gates before submission
The rule and official REG-32 instructions require more than a completed form:
- Returns: for an application filed on or after 1 April 2026, furnish at least one tax period's returns and every return due from the effective registration date through the application date. Before that date, the minimum was three months.
- Registration particulars: complete necessary amendments before withdrawal. The official instructions require no amendment application to be pending when REG-32 is filed.
- Cancellation proceedings: section 29 proceedings can prevent filing; if commenced after filing and still pending, Rule 14A(13) provides for rejection and excludes the stated deemed-approval route.
- Authentication: complete the required Aadhaar/biometric process. A saved or submitted draft without the required authentication is not proof of an ARN.
- Pending period: GSTN says core amendments, non-core amendments and self-cancellation applications cannot be filed while the submitted REG-32 is pending.
GSTN's 21 February 2026 advisory states separate 15-day windows for submitting a created draft and completing authentication after submission. Monitor each deadline independently; do not treat this as a promised withdrawal-approval time.
Give each action an owner and proof
| Owner | Working record | Completion evidence |
| Accounts preparer | Month-wise B2B output-tax schedule and contract forecast | Invoice-level totals reconciled to source records |
| Tax reviewer | Eligibility, due-return and amendment/cancellation checks | Dated review and unresolved questions |
| Authorised signatory | Portal application and authentication | Filed REG-32, ARN and authentication status |
| Compliance owner | Notices, order and effective-month calendar | Actual REG-33 or REG-05, order date and next action |
Use a secure agreed handover for the detailed documents. A first enquiry needs only the GSTIN's current scheme status, months involved and the problem description—not passwords, OTPs, Aadhaar copies or client invoices.
How Truetal helps—and where it stops
Truetal supports traceable invoices, accounting records and GST working data for human review. Those records can support an accountant's separately reviewed monthly B2B tax working and handover pack.
Truetal does not automatically determine Rule 14A eligibility, monitor its cap as a dedicated feature, submit REG-32, issue REG-33, or directly file GST returns. The authorised taxpayer and adviser must verify the legal position and act on the official portal. Ask for help organising the records and scoping the next review, not a guaranteed registration or withdrawal outcome.
Frequently asked questions
Is the Rule 14A limit ₹2.5 lakh of turnover?
No. The test is monthly output tax on supplies to registered persons, including CGST, SGST or UTGST, IGST and compensation cess. It is not annual turnover, invoice collections or the net cash payment after using ITC. General GST-registration applicability is a separate question.
Can a freelancer choose Rule 14A?
A service supplier applying under Rule 8 can consider the option if the Rule 14A conditions are met. Check monthly B2B output tax, Aadhaar requirements, existing registrations under the same PAN in that State or UT, and likely invoice peaks. Being a freelancer does not by itself establish eligibility.
How many returns are needed to withdraw after 1 April 2026?
At least one tax period of returns, together with all returns due from the effective date of registration through the withdrawal-application date. Do not describe one tax period as one month for every filing frequency. Other withdrawal conditions must also be satisfied.
Does submitting REG-32 immediately remove the Rule 14A limit?
No. Submission or an ARN is not the withdrawal order. Rule 14A(11) permits reporting above the specified B2B output-tax limit from the first day of the month after the REG-33 order month. Retain the actual order and its date.
Does withdrawal under Rule 14A cancel the GSTIN?
No. REG-32 requests withdrawal from the Rule 14A option, not cancellation of GST registration. REG-33 is the order allowing that withdrawal. GST registration and the applicable ongoing compliance obligations continue.