A company application brings more moving parts: company PAN and incorporation details, directors or promoters, an authorised signatory, board authority, registered and operating addresses, and DSC-based verification where required.
That is why this guide starts with the decision, not the form. The goal is to leave you with a short evidence list, a clear owner and a next action that does not overstate what software or a portal screen can decide.
The Short Answer
The company—not its director—is the taxable person. Use the company PAN and exact incorporation name, disclose promoters/directors as required, appoint the authorised signatory and prepare principal-place evidence. Company and LLP applications require the prescribed digital-signature route on the portal. Registration remains State-specific even though aggregate turnover is tested PAN-wide.
Last reviewed: 30 September 2026. Due dates, portal validations and notification-based exceptions can change. Verify the live portal and current primary source before acting.
In Plain Words
Map where the company actually makes supplies before filing. A registered office, warehouse, branch, project site and fulfilment location can have different GST consequences. Do not copy the MCA registered-office address into every GST application without testing the real principal place of business in that State.
Use three separate columns in your working: what your books say, what the GST system says, and what the law or current official guidance requires. Those columns often overlap, but they are not interchangeable. Keeping them separate prevents a software status or portal total from becoming an unsupported tax conclusion.
Why This Problem Happens
Teams usually begin with a remembered threshold, a dashboard number or a message from another party. The underlying evidence arrives later and may tell a different story. Names, GSTINs, periods, document numbers, State rules, amendments and timing can each change the answer.
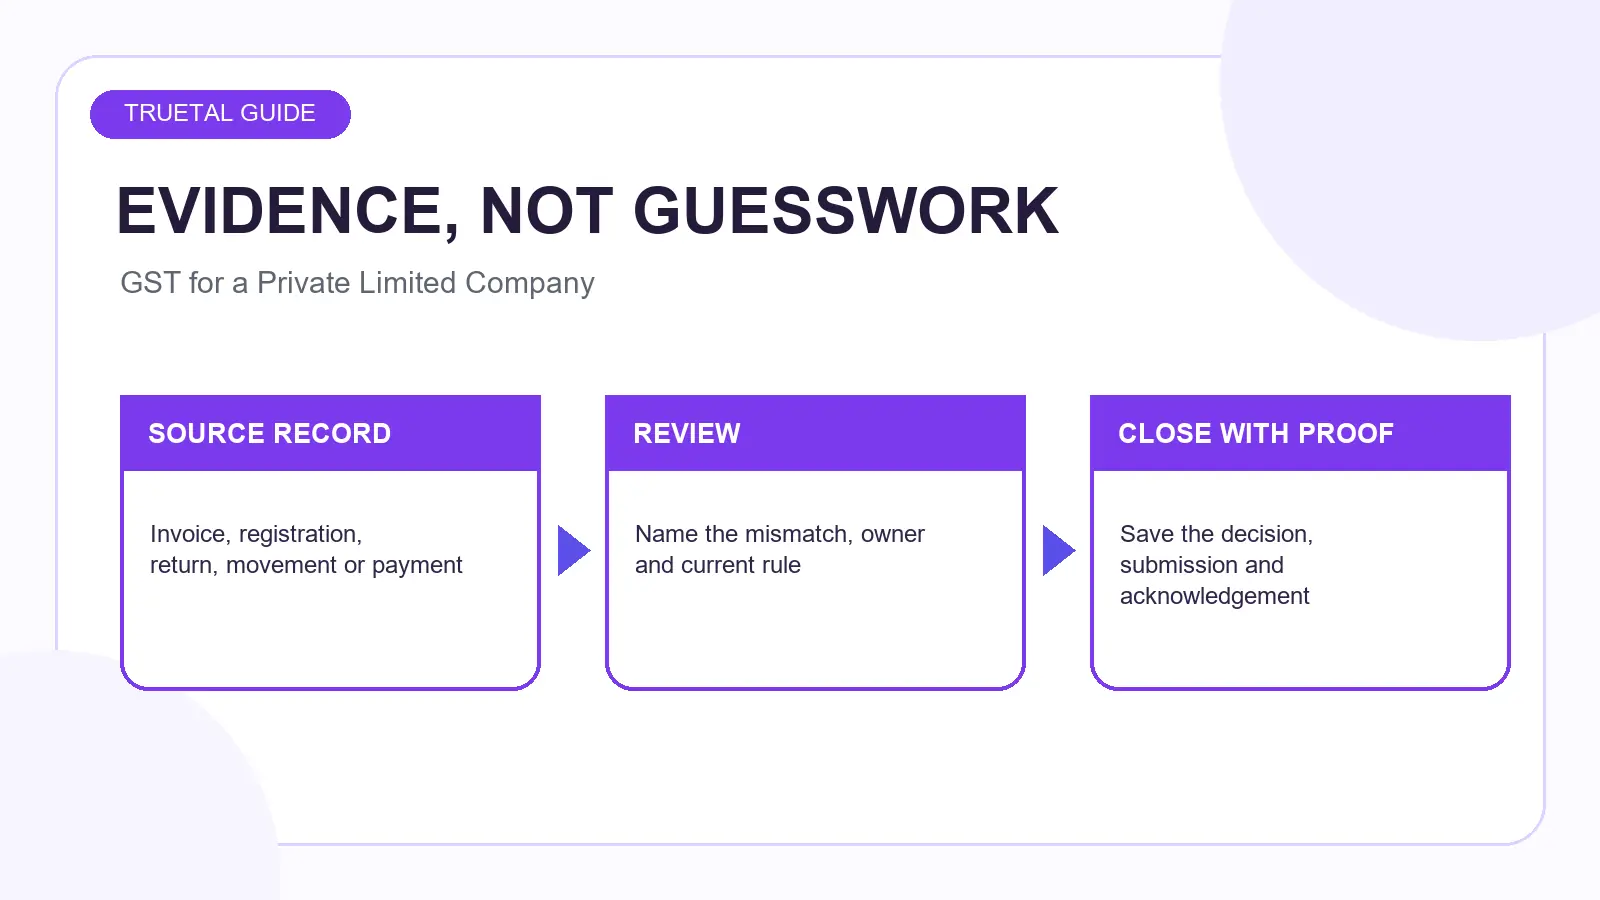
The practical fix is a repeatable review trail. Record the source, the period, the exception, the person responsible and the evidence that closes it. If a fact changes later, update the working rather than silently rewriting history.
The Decision Framework
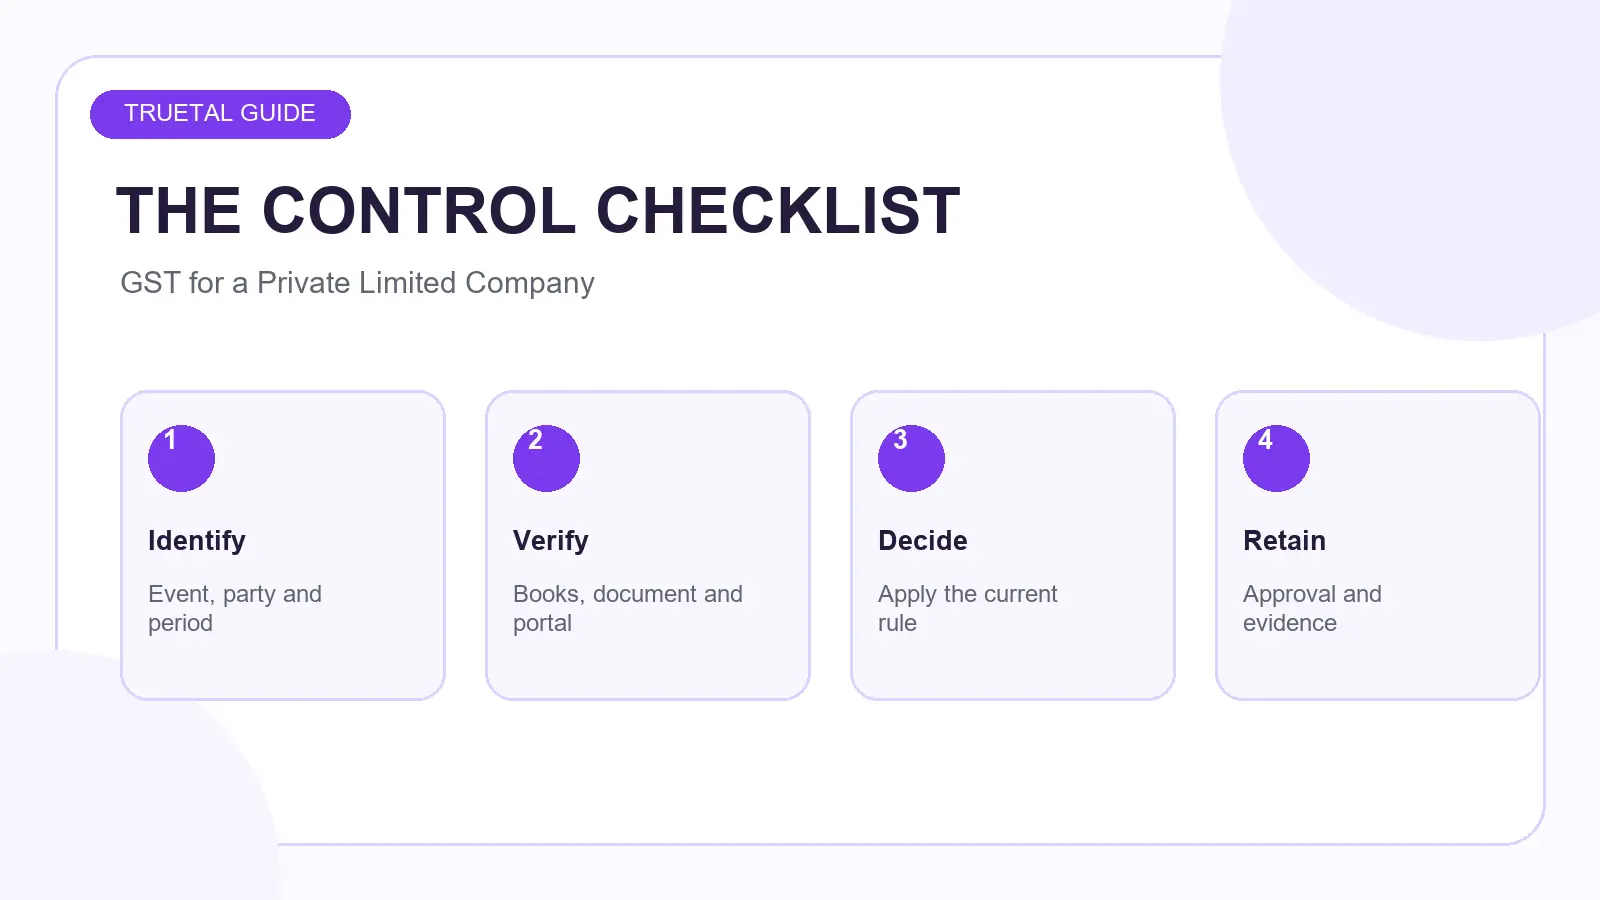
- Identify the event. What registration, return, invoice, movement, payment or notice is actually in question?
- Fix the period and parties. Confirm GSTIN, PAN, State, counterparty and relevant tax period.
- Compare the evidence. Put source documents, books and portal data side by side.
- Apply the current rule. Use the official source linked below and record any exception.
- Approve and retain proof. Keep the working, submission and acknowledgement together.
Step-by-Step Checklist
- Map States, warehouses and supply locations. Add the supporting record to the working and assign a named owner before moving to the next step.
- Match company PAN, incorporation name and registered details. Add the supporting record to the working and assign a named owner before moving to the next step.
- Approve and document the authorised signatory and DSC access. Add the supporting record to the working and assign a named owner before moving to the next step.
- File, verify, track ARN and review certificate details. Add the supporting record to the working and assign a named owner before moving to the next step.
Do not mark a step complete because someone says it was done. Mark it complete when the relevant source document, portal evidence or approval is attached.
Worked Example
A Mumbai company with a Bengaluru warehouse should not assume one Maharashtra GSTIN covers dispatches from Karnataka. The team should map stock locations and supply flow, then prepare the company documents, local place-of-business evidence and authorised-signatory records for each required registration.
The numbers and names in this example are illustrative. The control is the important part: preserve the original record, explain the difference and record the authorised decision. That creates a file another accountant or officer can follow without guessing.
Documents and Evidence to Keep
- certificate of incorporation and company PAN
- director/promoter details
- board resolution or authorisation
- principal-place evidence
- DSC and signatory contact access
Keep the final submission or action proof beside this pack. A screenshot without the underlying source, or a source document without the filed acknowledgement, leaves half an audit trail.
Exceptions and Edge Cases
The answer can change where there are several GST registrations under one PAN, supplies across States, exports, e-commerce operators, reverse charge, amendments, credit notes, cancelled documents or a portal notice. Treat each as a separate branch in the working.
When two official pages appear inconsistent, prefer the later notification, circular or current portal manual and record the date checked. Old official FAQs can remain online after a rule or system validation changes.
Common Mistakes
- using a director PAN as applicant
- copying one address across States
- leaving DSC setup until submission day
- failing to plan registrations around inventory locations
These mistakes share one pattern: a conclusion is made before the evidence is reconciled. Slow down at the decision point, not after submission.
How Truetal Helps — and Where It Stops
Truetal can help you organise business identity, invoice and accounting records after registration and give the team a clear place to continue the GST workflow.
Truetal does not submit GST registration applications or act as your authorised GST practitioner. The CTA opens a conversation so you can explain the case and identify the right next step.
That boundary is deliberate. Software should organise evidence, highlight exceptions and preserve decisions; it should not invent legal certainty or silently post a tax-affecting conclusion.
FAQ
What should I check first: GST for Private Limited Company?
Map States, warehouses and supply locations. Start with the source facts and the current official portal or notification. A headline threshold or a verbal assurance is not enough when the answer depends on entity, period, State, document type or transaction flow.
Which records should I keep?
Keep certificate of incorporation and company PAN, director/promoter details, board resolution or authorisation, plus the final acknowledgement, working and approval. Records should show what the business knew, what decision it made, who approved it and what was finally submitted or changed.
What is the most common mistake?
A common mistake is using a director PAN as applicant. The safer control is to preserve the source record, name the precise exception and close it with evidence rather than changing a number simply to make two totals agree.
How does Truetal help?
Truetal can help you organise business identity, invoice and accounting records after registration and give the team a clear place to continue the GST workflow. Truetal does not submit GST registration applications or act as your authorised GST practitioner. The CTA opens a conversation so you can explain the case and identify the right next step.
The Takeaway
Start with the source record, separate books from portal data, apply the current rule and close the exception with proof. Ask About Company GST when you are ready to turn the issue into a controlled next step.
Related Reading
- GST Registration Documents Checklist
- GST Registration Online: Documents, Process, Cost & Time
- GST Registration for New Business: Step-by-Step Checklist
- Explore Truetal’s connected business workflows
- Talk to the Truetal team about your workflow
Sources
- CBIC — CGST Act: registration, aggregate turnover and compulsory registration
- GST Portal — Apply for Registration as a Normal Taxpayer
- GST Portal — GST registration document checklist
- CBIC Instruction 03/2025 — registration document and verification guidance
This is general information, not legal or tax advice. Verify the facts, effective date and current notification for your business before acting.