The direct answer
The 57th GST Council recommended widening “Net ITC” for specified refund calculations:
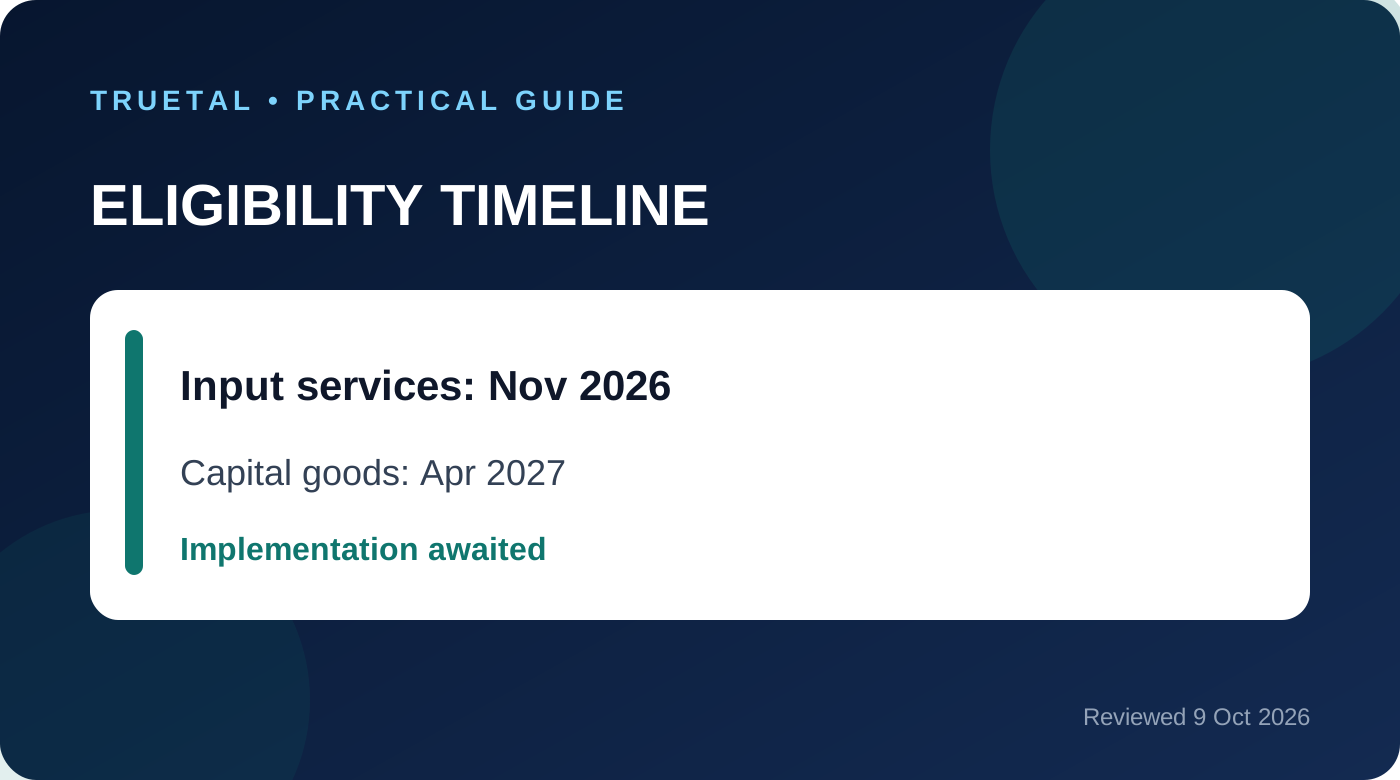
- eligible input-service ITC availed on or after 1 November 2026 would enter the inverted-duty refund formula; and
- eligible capital-goods ITC availed on or after 1 April 2027 would enter qualifying zero-rated-without-payment and inverted-duty refund calculations, attributable over 60 months.
These dates describe the proposed eligible ITC cohorts. They do not remove the need for the legal amendment and final Rule 89 formula.
Status as of 9 October 2026: Council recommendation and official explanatory FAQ published. Amendments to Section 54 and the CGST Rules are still required. Apply current Rule 89 until the change is legally commenced and reflected on the portal.
What may enter the proposed calculation
| Credit type | Proposed starting cohort | Proposed refund context | Key restriction |
| Input ITC | Existing rule continues | Eligible zero-rated/IDS claims | Existing conditions remain |
| Input-service ITC | Availed from 1 November 2026 | Inverted duty structure | There must first be inversion between input and output rates |
| Capital-goods ITC | Availed from 1 April 2027 | LUT/bond zero-rated and IDS | Only attributable 1/60 share per month |
| Blocked/ineligible ITC | None | None | Cannot enter the claim |
The inverted-duty condition still matters
Suppose goods used as inputs are taxed at 18% while the outward supply is taxed at 5%. That rate relationship can establish an inverted duty structure, subject to the law and exclusions. Under the proposal, eligible professional-service ITC availed from 1 November 2026 could then be included in Net ITC.
Now change the facts: inputs and output are both taxed at 5%, but consultancy services are taxed at 18%. The official FAQ says that higher input-service rate alone does not establish inverted duty structure. The proposal expands the credit included in a qualifying calculation; it does not create a new class of eligible claimant.
Worked capital-goods example
A qualifying manufacturer buys a machine and avails ₹6,00,000 of eligible ITC in April 2027. Under the proposed 60-month approach, the starting monthly attributable amount would be ₹10,000 before applying the complete Rule 89 formula, relevant-period conditions and any Rule 43 reversal.
It would be wrong to put the full ₹6,00,000 into the April refund claim. It would also be wrong to use this example as a filing formula before the final amended rule is published.
Preparation checklist
- Separate inputs, input services and capital goods in the purchase register.
- Record the exact month in which ITC was availed, not only the invoice date.
- Maintain an asset-level ITC schedule for acquisitions from 1 April 2027.
- Identify blocked credit before computing any refund.
- Apply Rule 42 and Rule 43 reversals where required.
- Confirm whether the claim is LUT/bond zero-rated, IGST-paid export or inverted duty.
- For IDS, prove rate inversion between inputs and output supplies first.
- Reconcile the proposed amount with GSTR-2B, GSTR-3B and the credit ledger.
- Recalculate after the final amended Rule 89 formula is notified.
Common mistakes
- Describing the proposal as an unrestricted refund of every unutilised credit.
- Assuming input-service tax alone creates IDS.
- Claiming the full capital-goods credit in one month.
- Including blocked Section 17(5) credit.
- Ignoring Rule 43 reversals or the period in which credit was availed.
- Treating the proposed dates as legal commencement without checking the amendment.
The takeaway
The proposal could unlock meaningful working capital for qualifying exporters and inverted-duty businesses. The safest action now is to improve classification and period tracking. A clean asset and ITC register will remain valuable whether the final formula matches the proposal exactly or changes during implementation.